 Aura Kasih
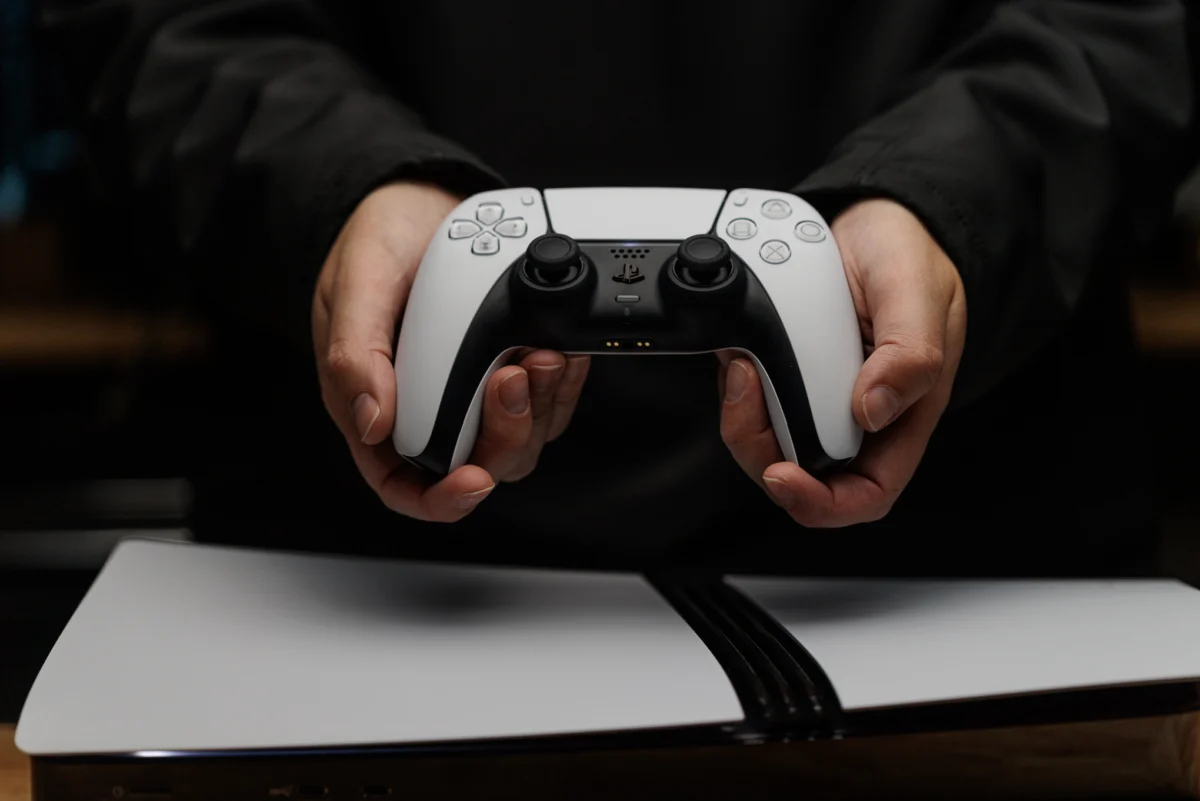
Contrary to earlier reports suggesting a rapid cessation of physical media production, Sony’s PlayStation division is reportedly extending the operational life of its disc manufacturing facilities, indicating a more nuanced approach to the industry-wide shift towards digital distribution. This recalibration suggests that the complete phase-out of optical media for video games will not be as abrupt as initially understood, with implications for both consumers and the broader gaming ecosystem.
The initial understanding, stemming from various reports, posited a significant and immediate reduction in disc output at Sony’s Thalgau, Austria plant, with projections suggesting a drastic decline in production capacity by January 2028. However, recent clarifications from a Sony DADC spokesperson indicate that the anticipated decrease in disc volume will be a more moderate 10 percent, rather than a reduction to 10 percent of current output. This distinction is crucial, implying that while the long-term trajectory remains digital, the immediate operational adjustments are less severe than previously conveyed.
This revised timeline for disc production cessation raises several pertinent questions about Sony’s strategy in managing the transition away from physical media. The Thalgau plant, a key node in Sony’s disc manufacturing network, has been the subject of speculation regarding its repurposing. Reports in July suggested that a substantial portion of the plant’s workforce, numbering around 300 employees, was undergoing retraining to shift focus towards microlenses, a component critical for optical storage and other technological applications. The ambiguity surrounding the extent of this retraining and the overall restructuring of the plant’s operations adds another layer of complexity to the narrative. While Sony DADC has not provided further details to external inquiries, the revised production figures suggest that the transition may be more gradual, allowing for a prolonged period of dual operation or a phased reduction in disc-related activities.
Several factors likely contribute to this more protracted approach. One significant consideration is the continued demand for physical media, even as digital sales dominate. While Sony has signaled its intention to discontinue the production of new game titles on disc after January 2028, the company will reportedly permit publishers to continue placing "re-orders for existing PlayStation disc games." This provision acknowledges a persistent market for older titles and the need to support their ongoing availability through physical channels. This could encompass collector’s editions, limited print runs, or simply the ongoing sales of established back-catalog titles that retain a dedicated consumer base. The ability for publishers to maintain access to disc production for these purposes underscores the reality that the digital-only future is not an instantaneous switch but a sustained evolutionary process.
The extended lifespan of disc production also carries broader implications for the concept of digital ownership in the gaming industry. The industry’s trajectory has increasingly favored digital licenses over tangible ownership, a trend that has sparked considerable debate among consumers and industry analysts. Sony’s own legal arguments, which have suggested that "reasonable consumers" cannot truly believe they own a digital game due to the nature of digital distribution and potential for multiple instances of a game to exist simultaneously, have fueled these concerns. This perspective challenges the traditional understanding of ownership, where possession of a physical copy traditionally confers a clear right to that product.

The shift away from physical media is not exclusive to Sony. Across the industry, publishers are navigating this evolving landscape. Microsoft’s "disc-to-digital" initiative, for instance, aims to facilitate the transition for consumers, yet the conspicuous absence of several major game publishers from this program highlights the varied approaches and potential friction points in this transition. The decision by some publishers to abstain from such initiatives could stem from various strategic considerations, including a desire to maintain direct control over their digital distribution channels, concerns about the economics of disc buy-back programs, or a commitment to their existing physical distribution networks.
Furthermore, the economic realities of game production and distribution play a significant role. While digital distribution offers advantages in terms of reduced manufacturing, shipping, and retail costs, physical media still holds value for certain market segments and for publishers seeking to maximize revenue streams. The continued production of discs, even at a reduced capacity, allows for a more controlled and potentially profitable winding down of physical operations, rather than an abrupt cessation that could alienate certain customer bases or disrupt established supply chains.
The strategic decision to extend disc production also reflects an understanding of consumer behavior and market dynamics. For many gamers, particularly collectors and those with limited or unreliable internet access, physical discs remain the preferred or only viable method of acquiring and playing games. A sudden discontinuation of disc production without adequate digital alternatives or robust cloud gaming solutions could alienate these segments of the market, potentially impacting sales and brand loyalty. The gradual approach allows Sony and its publishing partners to monitor consumer sentiment, adapt their digital offerings, and ensure a smoother transition for all stakeholders.
Looking ahead, the extended presence of disc production will likely coexist with a more aggressive push towards digital sales and subscription services. Sony’s PlayStation Plus service, for example, continues to evolve, offering a growing library of digital titles accessible through a subscription model. This dual strategy allows the company to cater to both traditionalists who value physical ownership and a new generation of gamers who embrace digital convenience and subscription-based access. The interplay between these two models will define the gaming landscape for the foreseeable future.
The industry’s move towards an all-digital future is an undeniable trend, driven by technological advancements, evolving consumer preferences, and the economic efficiencies of digital distribution. However, the recent revelations surrounding Sony’s disc production schedule suggest that this transition is a complex and multifaceted process, characterized by strategic adjustments and a recognition of the enduring value of physical media for certain market segments. The extended operational life of Sony’s disc manufacturing facilities underscores the nuanced reality of this digital evolution, indicating that the sunset of optical media will be a more gradual and strategically managed affair than initially anticipated. This recalibration is not merely a logistical adjustment; it signifies a thoughtful approach to managing market expectations, preserving access to a diverse gaming library, and navigating the intricate landscape of consumer ownership in the digital age. The industry’s ability to manage this transition effectively will ultimately shape the future of how games are bought, owned, and experienced.

 Safa Marwah
 Lisa Mariana